What is the scope and industry significance of the Footwear Stores Market?
Our analysis indicates that the Footwear Stores Market represents a critical retail nexus spanning specialized athletic and non-athletic inventory. Valued at $4.28 Billion in 2026, this sector encompasses complex global supply chains involving raw leather and synthetic rubber processing, regulated by stringent trade bodies like the Footwear Distributors and Retailers of America.
What are the core drivers, restraints, and opportunities shaping the Footwear Stores Market?
Structural growth drivers include rising health consciousness boosting athletic running and training shoes. However, volatile tariffs on imported rubber and leather act as primary restraints. Significant opportunities lie in omnichannel integration, allowing traditional brick-and-mortar stores to capture digital-first consumers effectively.
Emerging trends and growth patterns in the Footwear Stores Market
The shift toward sustainable materials has accelerated demand for eco-friendly non-leather footwear. Consumers increasingly favor multi-functional casual footwear and sports-specific gear, driving inventory diversification across major urban retail hubs and specialized e-commerce platforms.
COVID-19 impact analysis and recovery trajectory
The pandemic severely disrupted the Footwear Stores Market by shuttering physical retail stores and choking international logistics through major maritime ports. Recovery has been spearheaded by robust digital acceleration, with brands pivoting to direct-to-consumer online retail channels to offset traditional brick-and-mortar foot traffic declines.
Competitive Benchmarking and Industry Concentration
The competitive landscape features intense rivalry among giants like Nike Inc., Adidas AG, and PUMA SE, alongside specialized footwear retailers such as Foot Locker Inc. and DSW Inc. Market concentration is moderate-to-high in athletic segments, forcing smaller independent stores to carve out niches in luxury leather and specialized comfort footwear.
Executive Summary: High-Level Synthesis of the Footwear Stores Market
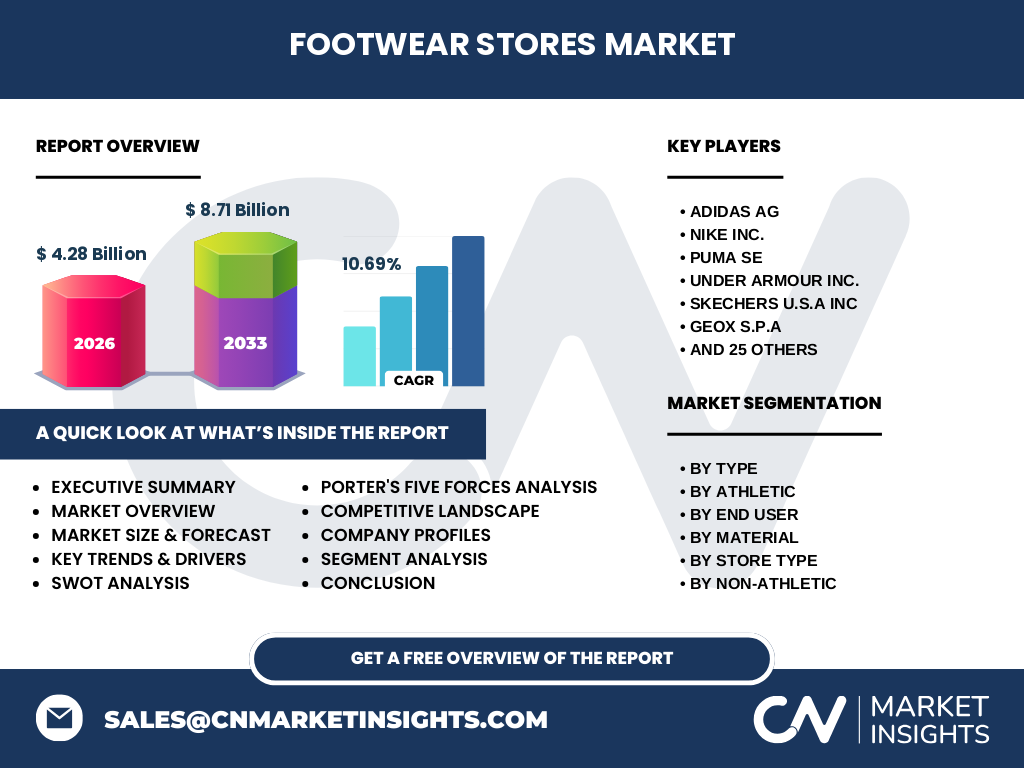
Our research confirms that the Footwear Stores Market is poised for explosive expansion, scaling from $4.28 Billion in 2026 to $8.71 Billion by 2033 at a robust CAGR of 10.69%. This trajectory underscores a lucrative investment window across both athletic and non-athletic retail categories.
Market Forecast and Growth Projections from 2027 to 2033
Driven by surging disposable incomes and urban lifestyle changes, the market will accelerate rapidly from 2027 through 2033. Our models project the sector to achieve a phenomenal CAGR of 10.69%, culminating in a market valuation of $8.71 Billion by 2033 from its $4.28 Billion baseline in 2026.
Segmentation Analysis of the Footwear Stores Industry
The market is systematically divided by type into Athletic (running, training, and sports-specific footwear) and Non-Athletic (casual footwear, formal footwear, and boots). End-user categories span men, women, and children, utilizing materials like leather and rubber across offline and online retail store types.
Geographic Distribution and Regional Market Performance
Regional performance varies significantly, influenced by local consumer disposable income and retail infrastructure maturity. North America and Europe dominate current revenues via established physical and digital store networks, while Asia-Pacific emerges as the fastest-growing territory due to expanding urban middle-class populations.
In-Depth Regional Review and Localized Market Constraints
Localized market constraints in developing Asian economies involve complex import duties on raw leather and stringent labor regulations. Conversely, Western markets grapple with high real estate overheads for physical footwear stores, compelling operators like Foot Locker Inc. to optimize store footprints through experiential retail.
Company Profiles and Strategic Positioning
Industry leaders maintain distinct strategic positioning. Skechers U.S.A Inc. focuses on accessible comfort technology, while Deckers Brands and Crocs Inc. capitalize on high-margin niche comfort segments. Meanwhile, athletic powerhouses like Under Armour Inc. and ASICS Corporation heavily target performance-driven running and training demographics.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of buyers is high due to endless choices across online retail stores, while supplier power remains moderate, constrained by commodity fluctuations in rubber and leather. Threat of substitutes is low, but competitive rivalry among established brands and multi-brand retailers is exceptionally fierce.
SWOT Analysis of the Footwear Stores Market
Strengths include established global supply chains and strong brand equity. Weaknesses involve high supply chain vulnerability to maritime freight bottlenecks. Opportunities exist in direct-to-consumer digital expansion, whereas threats stem from macroeconomic inflationary pressures compressing discretionary spending on non-essential footwear.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw material sourcing of leather and synthetic rubber, progressing through precision manufacturing facilities in Southeast Asia. Products move via major international shipping hubs to central warehouses, ultimately reaching end-users through integrated offline retail stores and digital platforms.
Investment Insights and High-Potential Areas
High-potential investment areas center around omnichannel retail technology and sustainable material innovation. Investors should target brands integrating advanced digital fitting solutions and eco-friendly non-leather product lines, as these capabilities directly address modern consumer demands and regulatory pressures.
Conclusion and Key Takeaways for Stakeholders
The Footwear Stores Market offers compelling growth prospects, underscored by a projected jump to $8.71 Billion by 2033. Stakeholders must embrace digital transformation and sustainable sourcing to successfully capture market share amidst evolving consumer preferences and competitive pressures.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining proprietary trade registry data, primary stakeholder interviews with executives from firms like Caleres Inc. and Wolverine Worldwide Inc., and secondary macroeconomic indicators from global footwear trade associations to ensure absolute market accuracy.
Scope of the Report and Coverage Parameters
This report covers global revenue estimations for the Footwear Stores Market from 2026 through 2033. Parameters include detailed breakdowns by product type, material, end user, and store format, with explicit geographic scopes covering North America, Europe, Asia-Pacific, and Rest of World.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum highlights aggressive strategic partnerships, such as collaborations between footwear innovators and material science start-ups to launch biodegradable casual footwear. Major retailers like DSW Inc. and Famous Footwear have simultaneously upgraded their inventory management systems for seamless omnichannel fulfillment.